Credit Cards
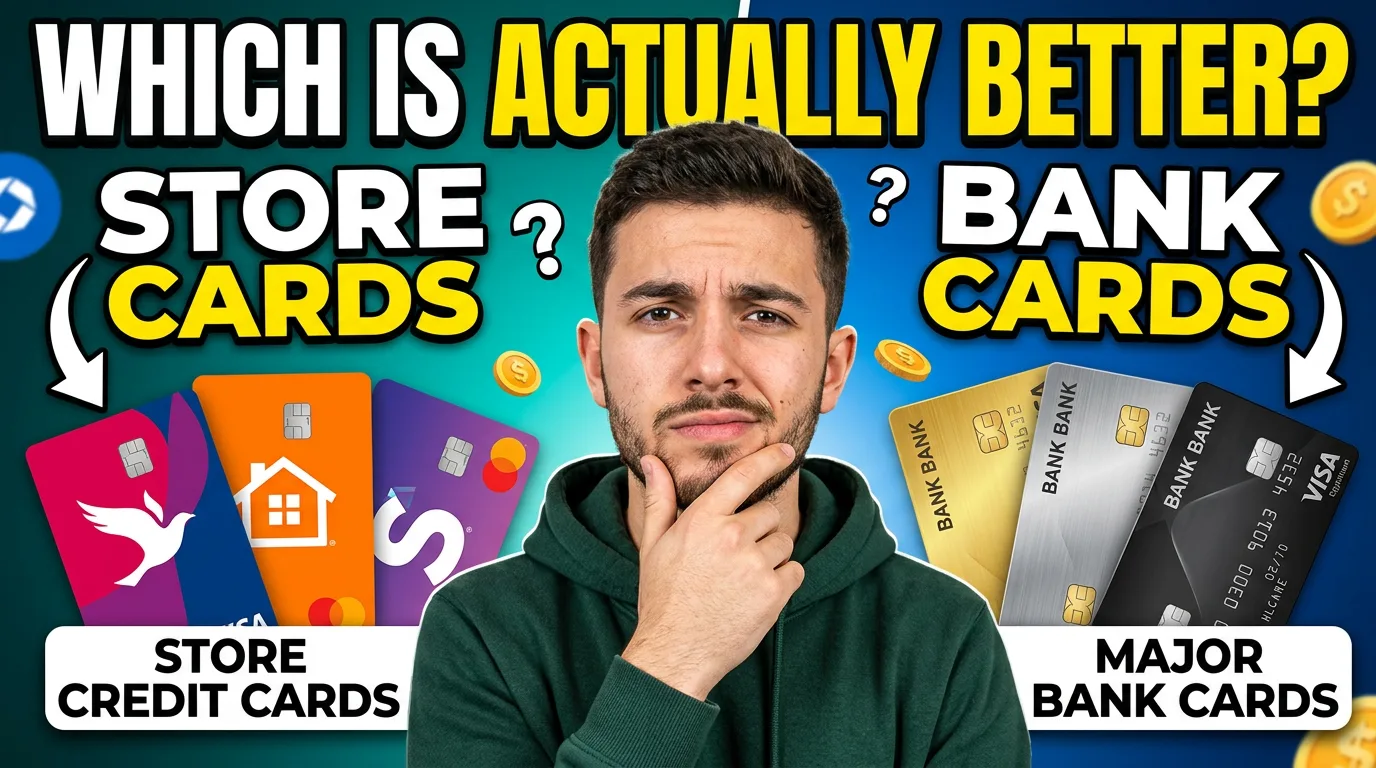
“Would you like to save 20% today by opening a store card?” It’s one of the most common pitches in American retail, and it works because the discount is real and the application takes about ninety seconds. But a store credit card and a general-purpose bank credit card are structurally different products, different underwriting, different pricing, different places you can use them. This guide breaks down exactly how retail cards compare to cards from major national banks like Capital One, Chase, Discover, American Express, Barclays, Bank of America, Navy Federal, and US Bank, so you can decide which type actually fits what you need.
Every brand named in this article is used only as a factual, structural example who issues what kind of card, which network it runs on, how approval odds typically compare, never as a recommendation or a claim about any specific current rate, reward, or offer, since those change constantly and aren’t something a general guide can verify as current.
Quick answer: are store credit cards or major bank credit cards better?
Neither is universally “better”, they’re built for different situations. Store credit cards, like those offered through Home Depot, Kohl’s, or Victoria’s Secret, are generally easier to get approved for, often with lower credit score requirements, and typically offer a strong discount on your first purchase. Their tradeoffs are real: research from the Consumer Financial Protection Bureau (CFPB) has found retail store cards carry substantially higher average APRs than general-purpose cards, many charge the same high rate to every approved applicant regardless of credit quality, and most only work at one retailer or its family of brands (a “closed-loop” card) rather than everywhere.
Major bank credit cards, issued by national banks like Chase, Capital One, American Express, Discover, Bank of America, Barclays, US Bank, or credit unions like Navy Federal, are general-purpose cards usable anywhere a card network (Visa, Mastercard, Amex, or Discover) is accepted. They typically have more competitive interest rate ranges tied to your individual creditworthiness, more robust rewards structures, and stronger fraud protections in practice, but harder approval standards, especially for cards with strong terms. For most people, a general-purpose bank card should be the primary card, with a store card considered only when the discount is large enough to be worth a hard inquiry and the card is one you’ll actually use often.
What actually makes a card a “store card”
Store credit cards generally come in two forms:

- Closed-loop (private label) cards: These only work at the issuing retailer and its affiliated brands. A card like Victoria’s Secret’s store card is a classic example; it’s issued by a bank partner but can only be used for purchases with that retailer, not as a general-purpose Visa or Mastercard anywhere else.
- Co-branded network cards: These carry a retailer’s name and rewards structure but run on an actual payment network (Visa, Mastercard, or another), so they can be used anywhere that network is accepted, often with bonus rewards specifically at the partner retailer. The Costco Anywhere Visa® Card, issued by Citi, is a well-known example of this structure; it’s a genuine Visa card usable broadly, not a closed-loop card, even though Costco itself is the co-brand partner.
In both cases, the retailer whose name is on the card almost never actually issues the credit itself. A bank does. Home Depot’s consumer credit card, for instance, is issued by Citibank under a card agreement filed with the CFPB. Kohl’s card program is issued by Capital One. This structure matters because when you’re evaluating a store card’s terms, disputing a charge, or trying to understand its underwriting, you’re really dealing with the bank behind it, not the store’s own credit department.
Network vs. issuer: who actually approves you
It helps to separate two roles that get blurred together in casual conversation about “credit cards”:
- The network (Visa, Mastercard, American Express, Discover) builds the payment infrastructure and determines where a card can be used. Networks set the rules merchants follow to accept a card and collect interchange fees on transactions.
- The issuer (a bank or credit union, think Chase, Capital One, Bank of America, Barclays, US Bank, or Navy Federal Credit Union) is who actually extends you credit. The issuer reviews your application, sets your credit limit and APR, decides whether to approve each individual purchase, and reports your account activity to the credit bureaus.

American Express and Discover are somewhat unusual in that they act as both network and issuer for most of their own cards, giving them more direct control end-to-end. Visa and Mastercard, by contrast, don’t issue cards themselves at all; every Visa or Mastercard-branded card, whether it says Chase, Capital One, Bank of America, Barclays, or a store’s name on the front, is actually issued by a bank that has partnered with that network. Understanding this distinction explains why, for example, a Kohl’s card and a Capital One general-purpose card can both ultimately be issued by Capital One while functioning completely differently; one closed-loop, one general-purpose.
Approval odds: why store cards are easier to get
Store cards are generally easier to qualify for than premium bank cards for a few structural reasons: many closed-loop cards carry lower credit limits, which limits the issuer’s downside risk; because the card can only be used at one retailer, the issuer has a narrower, more predictable spending pattern to underwrite against; and store cards are often a loss-leader tied to driving in-store sales and the discount itself, rather than a standalone profit center built primarily on interest income from a broad customer base. This is part of why store cards are frequently recommended as a starting point for people building credit from scratch or recovering from past credit problems; see Easiest Credit Cards to Get Approved For for more on that approach.
Major bank cards vary enormously in approval difficulty. Entry-level cards from issuers like Capital One or Discover, often built specifically for building or rebuilding credit, can be comparably accessible to store cards. Premium travel or rewards cards from banks like Chase or American Express typically require good-to-excellent credit and sometimes an established relationship or minimum income. Some issuers, including several of the banks named above, also offer “pre-approval” or “pre-qualification” tools that let you check your odds with a soft inquiry (no credit score impact) before formally applying; a genuinely useful step before submitting an application that would otherwise generate a hard inquiry.
Credit unions like Navy Federal add another wrinkle: membership eligibility. Navy Federal Credit Union, for example, restricts membership (and therefore its credit card products) to service members, veterans, Department of Defense civilian personnel, and their families; you generally can’t apply for a Navy Federal card without qualifying for membership first, regardless of your credit profile.
The real cost difference: interest rates
This is where the two categories diverge most sharply, and it’s backed by federal research rather than anecdote. In a CFPB “Issue Spotlight” report on the cost of retail credit cards, the Bureau found that private label (store) cards averaged a 32.66% APR as of December 2024, compared to notably lower average rates on general-purpose cards. The report also found that roughly 90% of retail cards had a maximum APR above 30%, versus only about 38% of general-purpose cards, and that 19% of retail cards carried APRs at or near 35%, approaching the cap set by the Military Lending Act for servicemembers. Total interest and fee costs on private-label cards ran four to six percentage points higher, as a share of balances, than on general-purpose cards.
A related structural point from the same CFPB research: many retail cards charge one flat APR to every approved applicant “regardless of creditworthiness”, a practice that’s been substantially phased out on general-purpose bank cards, where your individual rate is tied to your credit profile within a published range. In other words, a store card doesn’t reward good credit with a better rate the way most bank cards do; a customer with excellent credit and one with only fair credit can end up paying the identical, often quite high, rate on the same store card.
This matters most if you plan to carry a balance rather than pay in full. If you always pay off the card each month, the APR difference is close to irrelevant. If there’s any chance you’ll carry a balance, a high-APR store card can turn a 20%-off discount into a net loss within a few months of interest. Understanding how credit card interest and APR actually work makes this math much easier to run for yourself before applying.
Where you can actually use the card
This is the most overlooked practical difference. A closed-loop store card, like a private-label Home Depot or Victoria’s Secret card, generally cannot be used anywhere except that retailer (and sometimes its sister brands). A co-branded card built on a real network, running on Visa, Mastercard, Amex, or Discover rails, can be used broadly, with bonus value concentrated at the partner brand.
Acceptance quirks show up even among general-purpose networks. Costco is a well-known example: its warehouses and gas stations accept only Visa-branded credit cards in person (the co-branded Costco Anywhere Visa® Card by Citi being the natural fit, though any Visa credit card works), while Costco.com and the Costco app also accept Mastercard for online orders. American Express and Discover currently are not accepted at Costco’s physical warehouses at all. This exclusivity arrangement reportedly stems from a negotiated deal that lowers Costco’s per-transaction merchant fees, a good reminder that even among major networks, acceptance isn’t universal everywhere.
| Card type | Where it works | Typical approval bar | Typical APR pattern |
|---|---|---|---|
| Closed-loop store card (e.g., a private-label retailer card) | One retailer (and affiliated brands) only | Lower | High, often flat-rate regardless of credit |
| Co-branded network store card (e.g., a retailer’s Visa/Mastercard) | Anywhere the network is accepted, with bonus rewards at the partner store | Moderate | Moderate-to-high, sometimes still flat-rate |
| General-purpose bank card (e.g., from Chase, Capital One, Amex, Discover, Bank of America, Barclays, US Bank) | Anywhere the network is accepted | Varies widely by product, low to very high | Individually priced within a published range based on creditworthiness |
When a store card actually makes sense
- You shop at that specific retailer often enough that the ongoing rewards or discounts outweigh the card’s limitations.
- You’re building or rebuilding credit and a store card is genuinely more accessible than a bank card right now, as long as you commit to paying it off in full every month given the typically high APR.
- The sign-up discount is large relative to the purchase you’re already making, and you’re confident you’ll pay the balance off before it accrues meaningful interest.
- You want a low-limit account specifically to keep spending capped while you build a track record.
When a major bank card is the better fit
- You want one card that works everywhere, not a wallet full of single-store cards.
- You carry a balance some months and want your rate tied to your actual credit quality rather than a flat high rate.
- You want rewards that apply broadly (cash back, travel points) rather than only at one retailer, see Travel Rewards vs. Cash Back Credit Cards for how to think about that tradeoff.
- You qualify for pre-approval or pre-qualification offers from national issuers and want to compare real, personalized terms before applying.
Frequently asked questions
What credit cards does Costco accept in-store?
Costco warehouses and gas stations accept only Visa-branded credit cards in person, any Visa card works, not just the co-branded Costco Anywhere Visa® Card by Citi. American Express, Mastercard, and Discover are not accepted at physical Costco warehouses.
Which credit cards does Costco accept online?
Costco.com and the Costco mobile app accept both Visa and Mastercard for online purchases, which is broader than the in-warehouse Visa-only policy.
Do store credit cards help build credit the same way bank cards do?
Yes, most store cards report to the major credit bureaus the same way general-purpose cards do, so on-time payments and low utilization help your score regardless of card type. The difference is in cost and flexibility, not in whether the account itself counts toward your credit history.
Is it bad to have multiple store cards?
Not inherently, but each application generates a hard inquiry and each new low-limit account can affect your average account age and overall available credit. A few well-managed store cards generally cause less concern than opening several in a short window purely to chase sign-up discounts.
What does “credit card pre-approval” actually mean?
Pre-approval or pre-qualification tools, offered by many major issuers, let you check your likely approval odds and estimated terms using a soft credit check that doesn’t affect your score. It’s not a guarantee of final approval; the formal application still involves a hard inquiry and full underwriting, but it’s a useful way to compare real offers before committing to an application.
Are store card interest rates always higher than bank card rates?
Not universally, but federal research has consistently found retail store cards average substantially higher APRs than general-purpose bank cards, with many charging the same high rate to every approved applicant regardless of credit quality, unlike most bank cards, which price individually based on creditworthiness.
References
- Consumer Financial Protection Bureau – Issue Spotlight: The High Cost of Retail Credit Cards
- Consumer Financial Protection Bureau – Credit card data: Small issuers offer lower rates
- Consumer Financial Protection Bureau – The Home Depot Consumer Credit Card Agreement (Citibank)
- CNBC Select – Credit Card Network vs. Card Issuer: What’s the Difference?
- CNBC Select – What Credit Cards Does Costco Accept?
- Navy Federal Credit Union – Membership Eligibility
- myFICO – How Owing Money Can Impact Your Credit Score
Related Guides
- How to Choose the Right Credit Card for Your Lifestyle: A Complete Checklist
- Easiest Credit Cards to Get Approved For: Bad Credit, No Credit History & Low Income
- Why Your Credit Card Application Got Denied (and How to Fix It)
- No Annual Fee Credit Cards: Are Annual Fees Ever Worth Paying?
- Travel Rewards vs. Cash Back Credit Cards: Which Actually Saves You More?
- Should You Carry Multiple Credit Cards? Authorized Users, Churning, and Portfolio Strategy



Leave a Reply