PAN Card
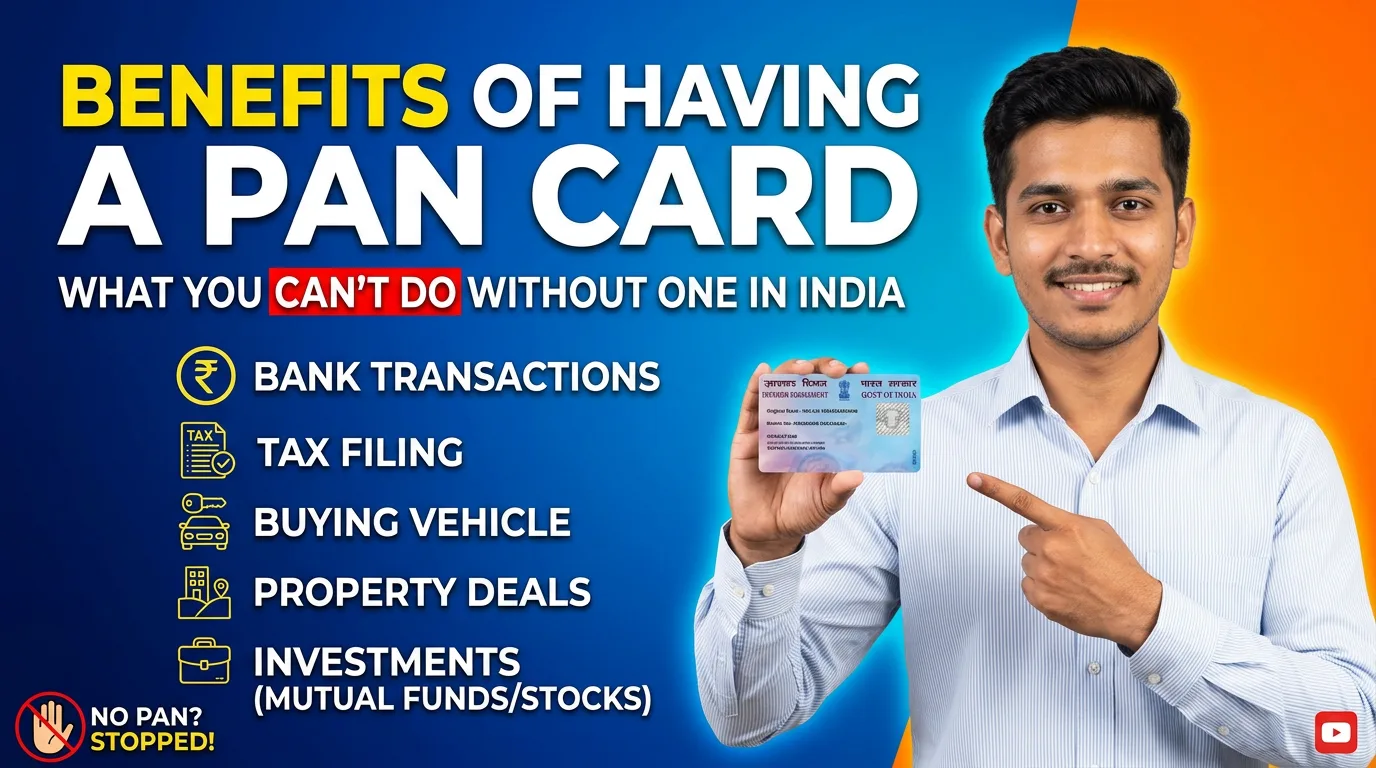
It’s tempting to think of a PAN card as a document you only need once a year, at tax-filing time. In practice, a Permanent Account Number (PAN) is one of the most-used financial identifiers in India, required for everything from opening a savings account to buying a car, investing in a mutual fund, or trading in stocks. Skip it, and you don’t just lose convenience; you often can’t complete the transaction at all, or you pay a steep tax penalty for trying. This guide walks through each major benefit with a concrete, step-by-step example of what actually happens at the counter or on the screen when PAN is missing, and covers PAN’s specific role in market investing and for NRIs. If you’re unclear on how PAN differs from a similar-looking number, see our PAN vs TAN comparison first.
Quick answer: what does a PAN card actually get you?
A PAN card lets you file income tax returns and claim refunds, complete KYC for a bank, demat, or mutual fund account, and quote it on high-value transactions like buying property, a car, or making large cash deposits, which is mandatory under Rule 114B of the Income Tax Rules. It also determines your TDS rate: without it, anyone deducting tax on your behalf must apply a flat 20% under Section 206AA instead of your normal, usually lower, rate. Without a PAN, most of these transactions either can’t be completed at all, or can only proceed with a Form 60 declaration and reduced limits, and you cannot file a return or get back tax that was already deducted from your income. For NRIs and foreign nationals, PAN is equally mandatory the moment they want to invest in Indian markets, alongside an NRE/NRO account and standard KYC documents.
1. Filing Income Tax Returns and Claiming Refunds
This is the original purpose under Section 139A of the Income Tax Act: PAN is the identifier the Income Tax Department uses to match your income, TDS, advance tax payments, and refunds across financial years. Without it, you cannot file an ITR, and any tax deducted on your behalf effectively cannot be reconciled or refunded to you. In practice this means a person without PAN who has tax deducted at a flat 20% rate under Section 206AA has no legal route to claim back the excess, since the return that would generate that refund can’t be filed without a PAN in the first place; the money simply sits with the government until the PAN issue is resolved.
2. Mandatory for Specified High-Value Transactions
Under Rule 114B of the Income Tax Rules, quoting PAN is compulsory for a defined list of transactions, including:
- Opening a bank account (other than a Basic Savings Bank Deposit Account)
- Cash deposits exceeding ₹50,000 in a single day
- Time deposits exceeding ₹50,000, or aggregating over ₹5 lakh a year
- Purchase or sale of immovable property valued at ₹10 lakh or more
- Purchase of a motor vehicle (other than a two-wheeler)
- Mutual fund purchases, life insurance premiums above ₹50,000/year, and securities transactions above specified limits
- Applying for a credit or debit card
Full details of the official transaction list are on the Income Tax Department’s Rule 114B page. If you don’t have a PAN, most of these transactions can only proceed with a signed Form 60 declaration, an extra step that many banks and dealers simply refuse to accept.
Walkthrough: buying a car without a PAN
Here’s what that looks like step by step at a dealership. A buyer selects a car, negotiates the on-road price, and moves to the finance and paperwork desk. The dealer’s billing system asks for PAN before it will generate the invoice, because Rule 114B treats the purchase of any motor vehicle other than a two-wheeler as a specified transaction. If the buyer has no PAN, the dealer typically offers Form 60 as a substitute declaration — but many dealerships, especially larger chains with automated billing software, simply don’t support Form 60 in their system and will decline to process the sale until a PAN is provided. Even where Form 60 is accepted, the buyer still needs to separately arrange vehicle financing, and virtually every NBFC or bank loan application requires PAN independently for credit checks, meaning the workaround at the dealer counter often doesn’t solve the financing step at all. The practical result is that most buyers without a PAN end up delaying the purchase by a few days to apply for an Instant e-PAN rather than push through with Form 60.
Walkthrough: opening a demat account without a PAN
This one is more absolute. A SEBI circular dated April 27, 2007 made PAN mandatory for all demat account holders and stock market participants, with no exceptions for residents and no Form 60 workaround available at all. When someone without a PAN tries to open a demat and trading account online through a broker, the KYC form simply won’t submit past the PAN field; it’s a required, validated field checked against the Income Tax Department’s database in real time, not just a paperwork formality to be filled in later. The account creation process halts entirely at that step; there is no partial account, no pending-PAN workaround, and no way to place even a single trade until a valid PAN is entered and verified. This is the sharpest contrast with something like opening a basic bank account, where Form 60 at least buys some time.
3. Opening Bank Accounts and Passing KYC
PAN is one of the core documents accepted for Know Your Customer (KYC) verification under RBI’s KYC master direction, alongside Aadhaar. Every scheduled bank asks for it when you open a savings, current, or NRI account, and demat and trading accounts won’t activate without it. If your PAN isn’t yet linked to your existing account, see our guide on linking PAN to a bank account.
4. Avoiding a Flat 20% TDS Rate
This is the benefit people underestimate most. Under Section 206AA, if you don’t furnish your PAN to whoever is paying you (an employer, a client deducting TDS on professional fees, a bank paying interest), they are required to deduct tax at source at a flat 20%, or the rate specified in the relevant section, whichever is higher; regardless of your actual tax slab. Furnishing your PAN brings that rate down to the normal applicable rate, which for most professional and contract payments is 2–10%.
5. Applying for Loans and Credit
Banks and NBFCs require PAN to check your credit history through CIBIL, Experian, and similar bureaus, and to comply with income-verification norms before sanctioning personal loans, home loans, vehicle loans, or credit cards.
6. Buying or Selling Property and Vehicles
Property registrations above ₹10 lakh and any motor vehicle purchase other than a two-wheeler legally require PAN from both parties. Registrars and dealers are required to record it and report the transaction.
7. Accepted as Photo ID Proof
Because it carries a photograph and is issued by a central government authority, PAN is accepted as valid ID proof for passport applications, many government services, and in situations where Aadhaar isn’t available or applicable; including for NRIs and foreign nationals who hold Indian PAN but not Aadhaar.
PAN’s Role in Mutual Fund and Stock Market KYC Specifically
Investing deserves its own section because the PAN requirement here is stricter than almost anywhere else in the financial system. PAN is mandatory under Rule 114B(d) for every stock market investor regardless of how small the portfolio is, and the SEBI-mandated KYC process that every registered broker, depository participant, and mutual fund house must complete treats PAN as a non-negotiable, system-validated field rather than a document you can substitute or defer. In practice this shows up in three places: opening a demat and trading account (no PAN, no account, full stop), completing mutual fund KYC through a fund house or a platform like a registrar and transfer agent (the same validation applies before your first SIP or lump-sum purchase can go through), and every subsequent transaction, since a PAN that later turns “inoperative”, most commonly from not being linked to Aadhaar, blocks new purchases and can flag existing holdings for extra scrutiny even though the units themselves aren’t forfeited. IPO applications submitted via ASBA or UPI are rejected outright without a valid PAN attached to the application, and derivatives trading (futures and options) inherits the same demat-account-level requirement. The practical lesson for anyone starting to invest is to confirm their PAN is active and Aadhaar-linked before opening an account, not after a purchase order has already failed.
PAN for NRIs and Foreign Nationals Investing in India
A Permanent Account Number is mandatory for all mutual fund and securities investments in India, including for NRIs, and this doesn’t change based on residency status, the SEBI and Rule 114B requirements apply identically to a resident and an NRI investor. What does change for NRIs is the surrounding setup: alongside PAN, an NRI investor needs either an NRE (Non-Resident External) or NRO (Non-Resident Ordinary) bank account with an Indian bank, with NRE accounts generally preferred for mutual fund investments since returns and principal are fully repatriable, whereas NRO account funds carry more restrictions on repatriation. KYC for an NRI investor typically also asks for a passport as the primary identity document, proof of NRI status (a visa, work permit, or overseas address proof), and a recent photograph, in addition to PAN itself. Foreign nationals who aren’t of Indian origin and want to invest directly in Indian equities generally do so through the Foreign Portfolio Investor (FPI) route rather than as individual retail investors, but PAN remains a prerequisite there too, since it’s the identifier Indian custodians and depositories use to register and report every trade. One detail that catches many NRIs off guard years later: if their PAN isn’t linked to Aadhaar (a linking requirement most NRIs are actually meant to be exempt from, but which often needs to be actively established with the Income Tax Department rather than applied automatically), the PAN can show as “inoperative,” blocking new investments and reverting TDS on any Indian income to the higher Section 206AA rate until it’s reactivated.
What Happens If You Don’t Have a PAN?
You can still transact using a Form 60 declaration for many Rule 114B transactions, but you’ll face a flat 20% TDS rate wherever tax is deducted at source, banks may cap your account transaction limits, and you cannot file an income tax return or claim a refund of any tax already deducted. For stock market and mutual fund investing specifically, there is no Form 60 substitute at all, the transaction simply cannot proceed. Freelancers and self-employed professionals in particular should read our guide on PAN requirements for the self-employed before taking on clients who deduct TDS.
Frequently asked questions
Is PAN only needed for filing income tax returns?
No. PAN is also required for KYC on bank and demat accounts, high-value transactions under Rule 114B, loan applications, and to avoid the higher 20% TDS rate under Section 206AA.
Can I open a bank account without a PAN?
You can open a Basic Savings Bank Deposit Account without PAN in some cases, but a regular savings or current account, or any account with sizeable cash deposits, will require either PAN or a Form 60 declaration.
What happens if I don’t give my PAN to a client who owes me TDS?
The client must deduct TDS at 20% (or the section’s specified rate, if higher) under Section 206AA, instead of the normal, usually lower, rate.
Does PAN work as identity proof like Aadhaar?
Yes, PAN is widely accepted as photo ID proof for passport applications and several government and financial services, which is especially useful for NRIs who may not have an Aadhaar.
Do minors need a PAN card?
A PAN can be issued to a minor if they hold assets or investments in their name, with a parent or guardian signing the application. It’s optional otherwise until they begin earning taxable income.
Can I open a demat account without a PAN using Form 60?
No. Unlike a basic bank account, demat and trading accounts have no Form 60 workaround, a SEBI circular from 2007 made PAN mandatory for all stock market participants, and the KYC form will not process without a validated PAN.
Do NRIs need an Indian PAN to invest in Indian mutual funds?
Yes. PAN is mandatory for all mutual fund and securities investments in India regardless of residency status. NRIs additionally need an NRE or NRO bank account and standard KYC documents like a passport and proof of NRI status.
References
- Income Tax India – Specified transactions requiring PAN (Rule 114B)
- Income Tax India – Apply for PAN
- Press Information Bureau – Cabinet approves the PAN 2.0 Project
- Protean eGov Technologies – PAN Services
- UTIITSL – PAN Card Services
- Bigul – Why PAN Card Is Mandatory for Demat Accounts, Mutual Funds and Stock Market Investing
- SBNRI – How NRIs Can Invest in Indian Mutual Funds

Leave a Reply