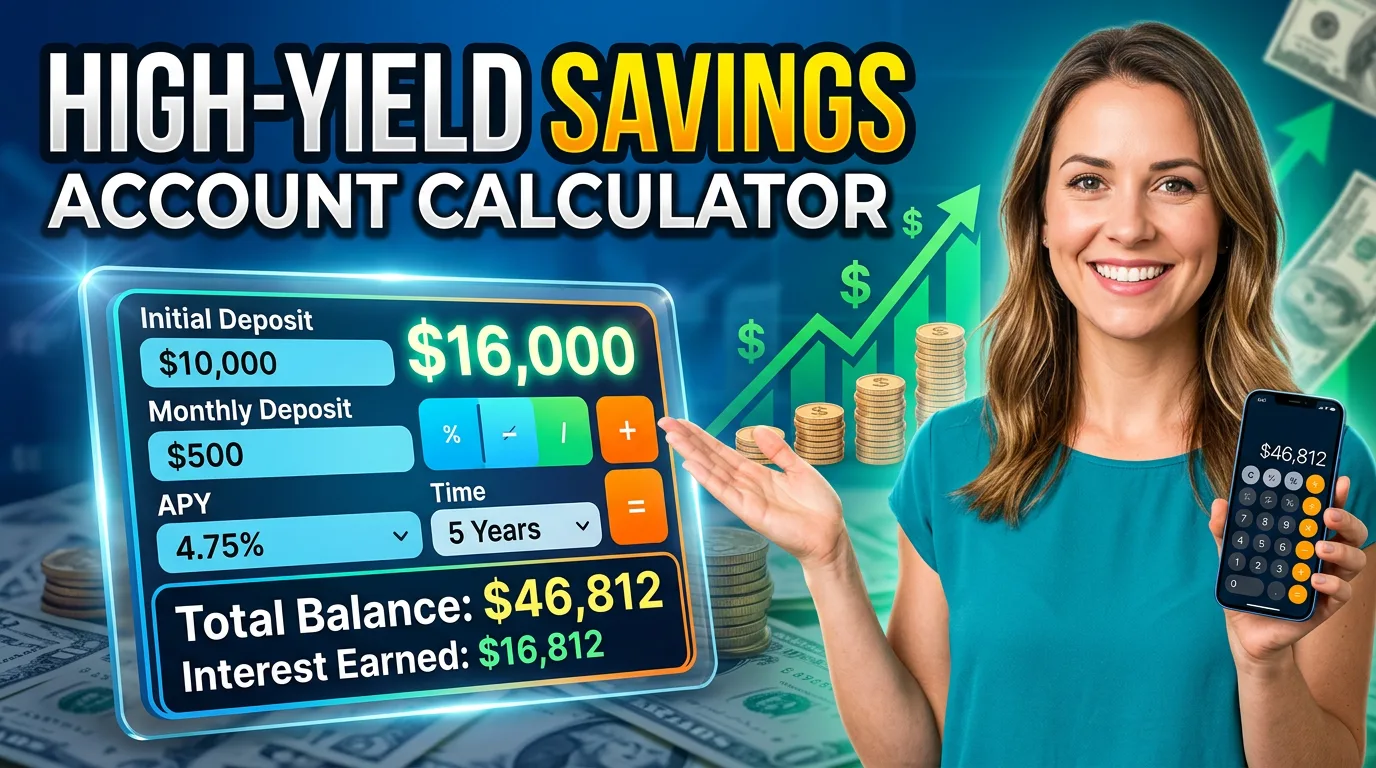
The average U.S. savings account pays around 0.38% APY, while the best online high-yield savings accounts have recently paid somewhere in the 4% to 4.5% range. On $10,000 held for five years with $300 added monthly, that gap alone can be worth thousands of dollars in interest you’d otherwise leave on the table. The calculator below shows the difference using your own numbers.
Quick answer: what makes a savings account “high-yield”
A high-yield savings account (HYSA) is simply a savings account that pays a meaningfully higher annual percentage yield (APY) than the typical bank average, usually because it’s offered online without the overhead of physical branches. It works the same way as any other savings account, insured deposits, easy access to your cash, variable interest that can rise or fall, the only real difference is the rate. Because interest compounds, a higher APY doesn’t just add a little extra each year; it compounds on itself, so the gap between a high-yield account and an average one grows faster than most people expect over a multi-year horizon.
The math: comparing two rates on the same deposits
The calculator projects the same starting balance and monthly deposit under two different annual rates: the APY you enter, and the FDIC’s published national average savings rate. For each rate, it applies the standard compound-interest formula:
Balance = P × (1 + r)n + PMT × [((1 + r)n − 1) / r]
where P is your current balance, PMT is your monthly deposit, r is the monthly rate (APY divided by 12), and n is the number of months. The difference between the two resulting interest totals is the extra return you get purely from choosing a higher-yield account with identical deposits and identical time. That comparison isolates the one variable, the rate, that a high-yield account actually changes.
It’s worth noting that APY already accounts for compounding, unlike a simple stated “interest rate,” so when comparing two accounts you should always compare APY to APY rather than a nominal rate to an APY, since a nominal rate understates the actual annual return.
Common mistakes with high-yield savings accounts
A frequent mistake is chasing a promotional APY that only applies to a small balance tier or expires after an introductory period, then reverts to a much lower rate — always check what the rate becomes after any promotional window ends. Another is ignoring that these rates are variable and move with broader interest-rate policy, so the APY you lock in today isn’t guaranteed to still be there next year; a rate cut can arrive with little warning. People also sometimes confuse a high-yield savings account with a certificate of deposit (CD, a CD typically pays a fixed rate for a fixed term with an early-withdrawal penalty, while a HYSA keeps your money liquid but its rate can change at any time. Finally, some savers underestimate how much of the benefit comes from consistent deposits rather than the rate alone; the rate advantage compounds faster the more you’re regularly contributing.
Frequently asked questions
Is a high-yield savings account safe?
At an FDIC-insured bank (or NCUA-insured credit union), balances are protected up to $250,000 per depositor, per institution, per ownership category, the same protection as a standard savings account. The higher rate isn’t compensation for extra risk; it mainly reflects lower overhead at online-only banks.
How often does a high-yield savings account’s rate change?
APYs on these accounts are variable and can change at any time, often tracking Federal Reserve policy moves. Banks are generally required to disclose rate changes, but there’s no fixed schedule guaranteeing how often or by how much a rate moves.
What’s the difference between APY and interest rate?
The interest rate is the nominal annual rate before compounding; APY (annual percentage yield) reflects the actual return after compounding is factored in. Because of this, APY is always the more accurate number to compare across accounts, and it’s the figure this calculator uses.
Can I lose money in a high-yield savings account?
Your principal isn’t at risk the way it would be in the stock market, and FDIC or NCUA insurance covers the balance up to the standard limits. The main “cost” is opportunity cost if inflation outpaces your APY, which erodes purchasing power even while the account balance itself only grows.
References
The 0.38% comparison figure reflects the FDIC’s published national average savings account rate; current high-yield APY ranges are drawn from recent published rate surveys of online savings accounts. FDIC and NCUA deposit insurance limits are set by federal law and detailed on each agency’s official site:
- FDIC National Rates and Rate Caps – national average savings account rate.
- IRS Topic no. 403, Interest received – how savings account interest is taxed.
Related guides
- Savings Calculator – project any starting balance and contribution at any rate.
- Savings Bond Calculator – estimate the value of a U.S. Series EE or Series I bond.
- Retirement Savings Calculator – project your balance to a specific retirement age.
- Savings Goal Calculator – work backward from a target amount to a required monthly deposit.
- Savings & Budgeting 101 guide – the fundamentals of budgeting and savings, plus links to every related guide.


Leave a Reply